The lowest price rarely comes from asking for it first. The best questions to ask motivated sellers uncover why they’re selling, when they need to move, what the property needs, and what price they’ll accept. Once you understand the seller’s priorities, ask what they’d consider for an all-cash offer with a two-day closing.
Price matters, but pushing too hard before you understand the seller’s situation can end the conversation before you learn what might make a deal work.
This guide covers direct questions to uncover a seller’s motivation, financial pressures, property challenges, and price expectations. You’ll also learn how to listen for useful details, build rapport without wasting time, and distinguish a firm asking price from room to negotiate.
Key Takeaways
- Ask what’s driving the sale, then listen for pressure points such as carrying costs, repairs, or managing a property from a distance.
- Discuss the mortgage balance, missed payments, and liens to understand what may affect the seller’s options and your offer.
- Explore the seller’s timeline and ask what they would accept for a fast, all-cash offer. Their response can reveal room to negotiate.
- Build trust by asking clear questions, listening without judgment, and tying your follow-up questions to what the seller actually says.
- Compare the seller’s price with the property’s condition and your deal numbers before deciding whether the opportunity makes sense.
1. Motivation examples including financial hardship and property management
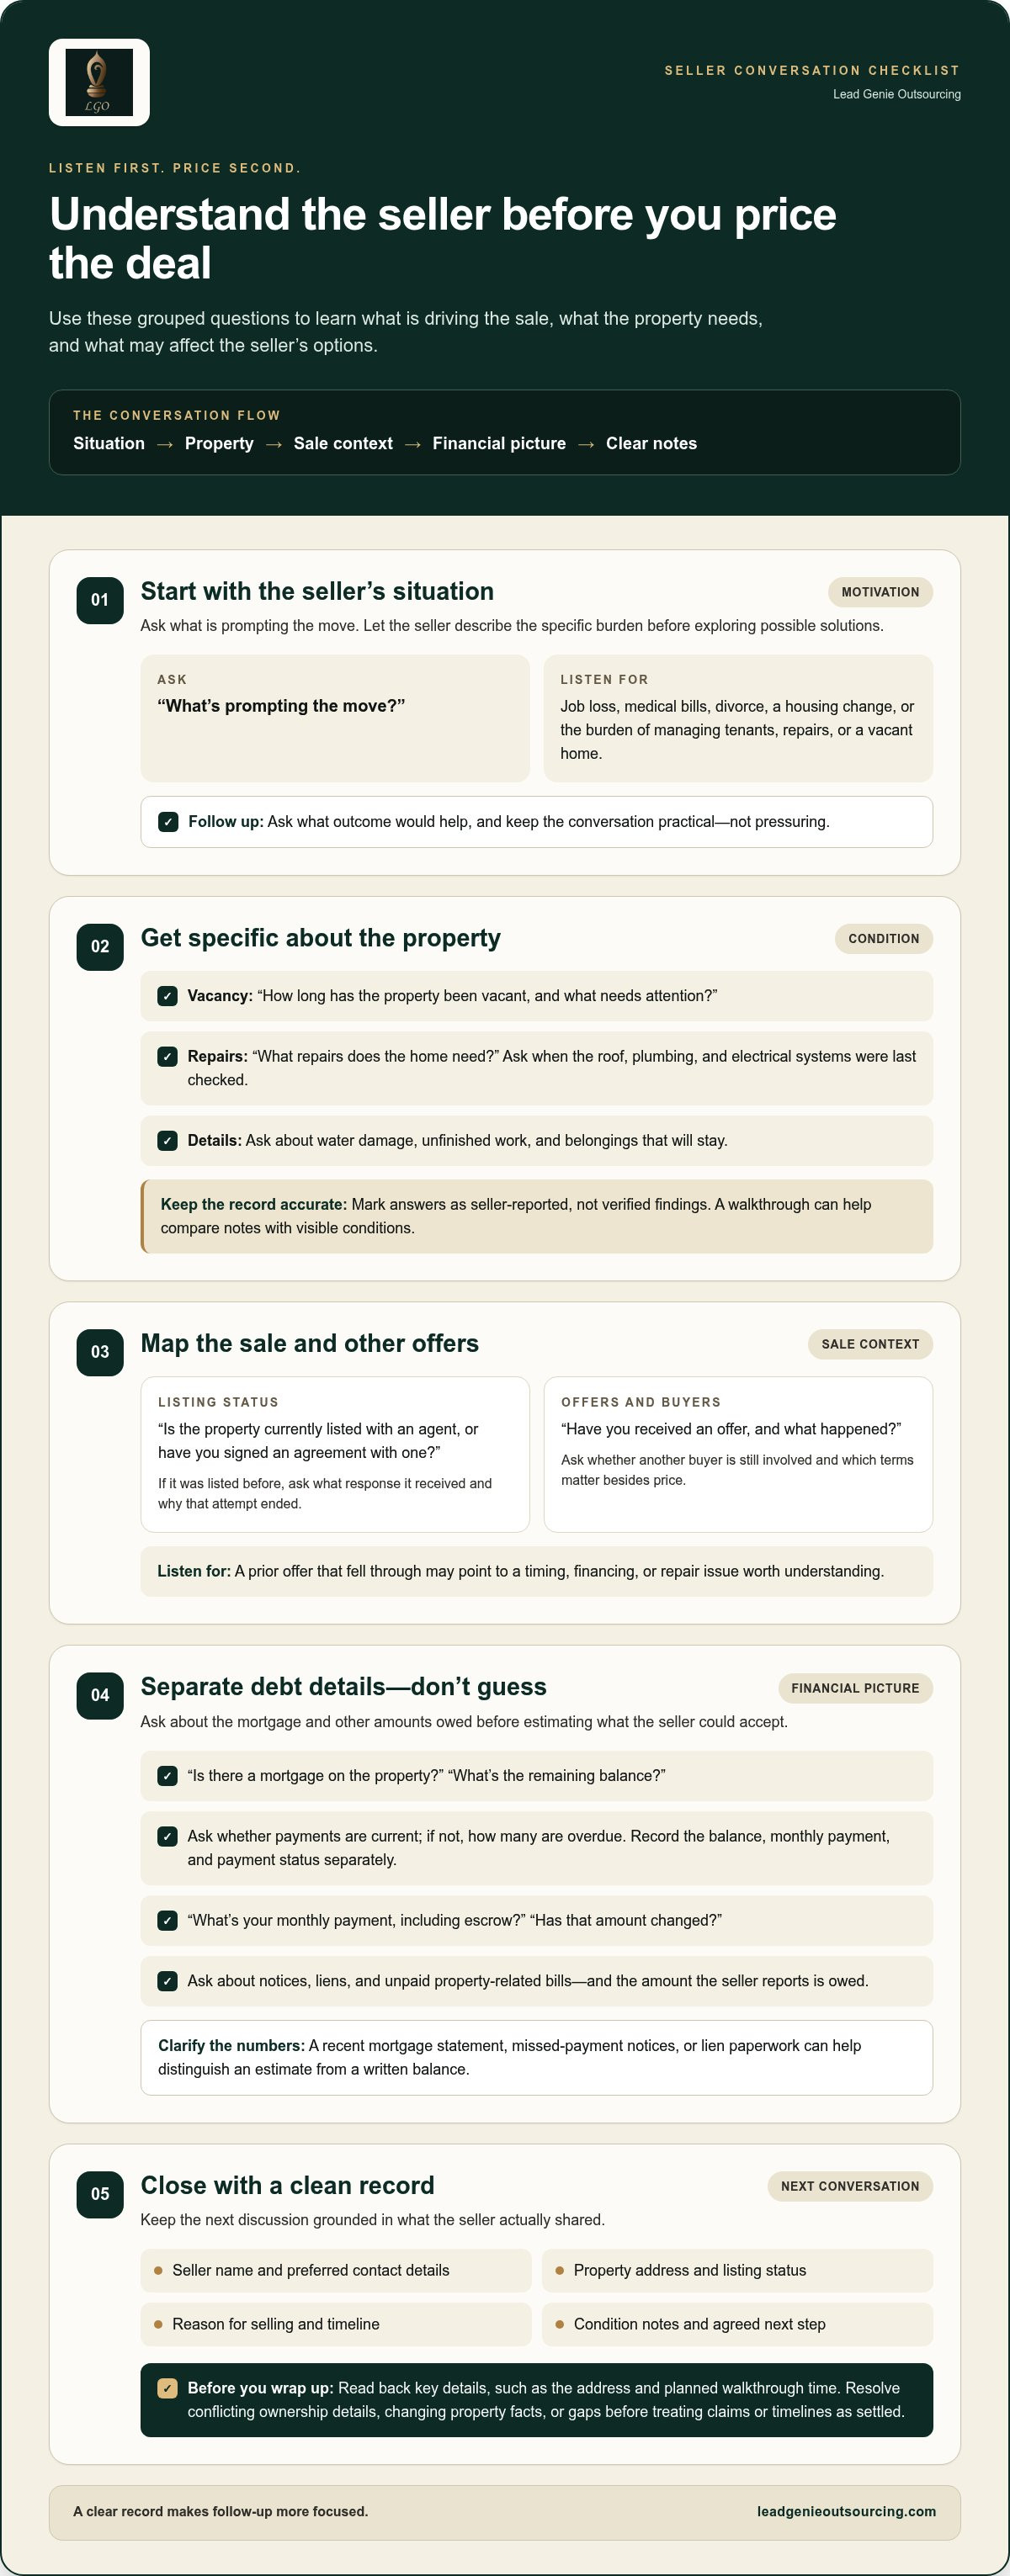
Start with the seller’s situation, not an assumption about their motivation. Ask, “What’s prompting the move?” A job loss, medical bills, divorce, or need for different housing may shape the sale. An out-of-state owner may be tired of managing tenants, coordinating repairs, or checking on a vacant property. Listen for the specific burden, then ask what outcome would help.
Vacancy can mean ongoing taxes, insurance, and maintenance costs, and an empty home may face vandalism. Ask, “How long has the property been vacant, and what needs attention?” If the owner can’t afford repairs, ask which problems are getting in the way of a sale. Keep the tone practical. Financial strain is not a reason to rush or pressure someone.
Ask about listing status early: “Is the property currently listed with an agent, or have you signed an agreement with one?” If the seller says yes, clarify who handles communication and whether an offer can be discussed directly. Ask whether the home was listed before, what response it received, and why that attempt ended. This shows what has already been tried.
To understand offers and other buyers, ask, “Have you received an offer, and what happened?” Then ask whether another buyer is still involved and which terms matter besides price. A prior offer that fell through may point to a timing, financing, or repair issue worth understanding.
Ask about condition with clear prompts: “What repairs does the home need?” and “When were the roof, plumbing, and electrical systems last checked?” Ask about water damage, unfinished work, and belongings that will stay. Record the seller’s answers as reported details, not verified findings. A walkthrough can help you compare those notes with visible conditions.
During the walkthrough, go room by room and note repair needs that may affect a future listing. For example, record damaged flooring, a leaking fixture, or an overgrown yard. Ask what work the seller has completed and whether receipts or contractor notes are available. Separate urgent defects from cosmetic updates to keep your follow-up focused.
Watch for red flags such as conflicting ownership details, changing property facts, or pressure to skip basic review. For an estate sale, clarify who is involved and who can answer questions about the property. Resolve gaps before treating the seller’s timeline or claims as settled.
Before ending the call, record the seller’s name, preferred contact details, property address, listing status, reason for selling, timeline, condition notes, and next step. Read back key details, such as the address and planned walkthrough time. A clear record keeps the next conversation grounded in what the seller actually said.
2. Asking about mortgages, liens, and missed payments
Ask directly about the mortgage before estimating what the seller could accept. Try, “Is there a mortgage on the property?” and “What’s the remaining balance?” Then ask whether payments are current and, if not, how many are overdue. Track the balance, monthly payment, and payment status separately, since each affects your assessment differently.
Follow up with, “What’s your monthly payment, including escrow?” and “Has that amount changed?” A payment that strains the seller’s budget may help explain the timeline, but it doesn’t establish the property’s value or available equity. Ask whether the seller has received notices about missed payments, liens, or other amounts owed against the property.
If the seller reports missed payments, use the reported number as a starting point, not a verified payoff figure. One suggested screening approach is to double the number of payments the seller reports as overdue, then verify the status through records. According to the Consumer Financial Protection Bureau, federal rules prevent a mortgage servicer from filing for foreclosure until a borrower is more than 120 days behind on payments. That fact doesn’t tell you the seller’s exact status or resolve the property’s debt.
Before a meeting, learn the remaining mortgage balance and estimate the property’s after-repair value. Compare those figures with the seller’s asking price and likely repair needs. A large gap between value and debt may leave room for options; little or no equity can narrow them. Don’t treat an estimated value as cash the seller can access. Other obligations may change the overall picture.
Ask, “Are there any liens or unpaid property-related bills?” and “Do you know the amount owed?” A lien can affect what remains after a sale, so record the type of claim and the amount the seller reports. Don’t promise that a particular debt can be cleared through a deal. First understand what the seller says is owed and what documents support that amount.
Ask the seller to share a recent mortgage statement, notices about missed payments, and paperwork for known liens. Property tax bills or payoff information can also help clarify the numbers. Keep requests focused and explain how each document helps you assess the deal. A recorded call captures the seller’s answers, but documents help distinguish an estimate from a written balance.
Log the mortgage balance, monthly payment, payment status, lien details, and after-repair value as separate fields. That makes gaps easy to spot before you discuss terms. For a structured way to capture a seller’s motivation, timeline, condition, and asking price, use this seller qualification framework.
3. Negotiating the seller's lowest acceptable price
Don’t open with “What’s your lowest price?” It can sound demanding before you understand the seller’s goal. First ask, “What price are you hoping to get?” Then follow with, “How did you arrive at that number?” The answers may show whether the seller is thinking about a payoff, a nearby sale, repairs, or the amount needed for their next move.
Next, connect price to timing. Ask, “When do you need the sale completed?” and “What happens if the property doesn’t sell by then?” A seller who needs to move soon may value a clear process more than a higher offer that takes longer. A flexible timeline may give the seller room to compare options. Don’t assume urgency automatically means they’ll accept a lower price.
Once you understand the timing, ask directly: “If I could make an all-cash offer and close in two days, what would you accept?” This gives the seller a concrete scenario instead of asking for an abstract discount. If they name a price, ask whether it’s firm or whether terms such as the closing date, included belongings, or repair handling could affect their decision.
Distinguish the asking price from the seller’s actual minimum. Try, “Is that the amount you need, or the amount you’d like to get?” Then ask, “What’s the least you’d consider if the terms fit?” Give the seller time to answer. Don’t fill the silence with a higher number or try to talk them out of their response.
As an investor, compare the seller’s number with the property’s after-repair value and the repairs you identified. The 70 percent rule is a guideline that a maximum offer should almost never exceed 70 percent of after-repair value. It can help account for repairs and unexpected expenses. Treat it as a deal-screening tool, not a substitute for checking the property, costs, and your resale plan.
If the seller rejects your offer, ask, “What part doesn’t work for you?” A concern about price calls for a different response than a concern about closing time or certainty. Adjust the terms only if the deal still works. A successful negotiation isn’t simply getting the lowest number. It’s reaching terms both sides understand and can act on.
Before ending the call, repeat the seller’s stated price, timeline, and key terms. Ask whether you got them right. Record the seller’s exact wording, then compare it with your numbers before making a written offer. This keeps the negotiation grounded in what the seller said, not an assumption made during a fast conversation.
4. Understanding the seller’s reasons for selling
Ask, “What’s making you consider selling now?” Then pause. The reason for the sale often explains the seller’s priorities better than a quick answer about price. If a landlord says tenant issues have become draining, ask which tasks are hardest and what a sale would help them stop managing. Keep follow-up questions tied to the seller’s words.
Separate the reason from the trigger. “How long have you been thinking about selling?” and “What changed recently?” can show whether the decision has been building or follows a new event. A seller who has planned to move for months may have different timing needs from someone facing a sudden change. Record both answers separately.
For a divorce or estate sale, ask who else is involved in the decision and what needs to happen before the property can be sold. Don’t assume one person’s preference speaks for everyone. If a family member handles calls while someone else owns the home, note each person’s role and agree on who should join the next conversation.
A seller hoping to sell before foreclosure may focus on speed, certainty, or avoiding more payment pressure. Ask, “What’s your main concern if the property doesn’t sell soon?” Then clarify the timeline and the outcome they want. Don’t use the situation as a reason to push for a lower price. Instead, learn which terms matter to the seller.
Listen for the difference between the stated reason for selling and the problem the seller needs to solve. “I’m tired of being a landlord” may mean they want to stop handling repairs, tenant calls, or vacancies. Ask which issue weighs most and whether they plan to buy another home, relocate, or leave the rental business. Their answer can guide useful follow-up.
Questions to ask motivated sellers should uncover facts without turning the call into an interrogation. Ask one clear question, listen, then reflect the answer: “So managing the rental from out of state is the main reason you’re selling. Did I get that right?” This gives the seller room to correct you and helps keep your notes accurate.
Close the discussion about motivation with a practical next step: “What would need to happen for you to feel ready to move forward?” The answer may point to a price, date, family discussion, or repair concern. Record the seller’s own words, the decision-makers involved, and the next action you both agreed on.
5. Building rapport with motivated sellers
Rapport starts with how you handle the first minute of a call. Give your name, explain why you’re reaching out, and ask whether now is a good time for a short conversation. If the seller sounds distracted, offer to call at a time that works for them. That choice gives the seller control and keeps the conversation from feeling like a pitch.
Use the seller’s own words to guide your next question. If they say, “I can’t keep up with this rental,” don’t jump straight to price. Ask which part has become hardest, such as tenant calls, repairs, or a vacancy. Then reflect their answer: “So the repair work is taking more time than you want to give it.” Be accurate, not performative.
Good strategies make the call feel like a conversation, not a checklist. Ask one question, listen without interrupting, and follow up on a detail the seller shared. If they mention moving closer to family, ask whether they have a target date. Avoid cramming questions about price, condition, and timing into one breath.
Keep your tone steady when a seller shares financial stress or family conflict. Don’t pry for personal details that don’t affect the property or sale. If the seller says medical bills are part of the reason, briefly acknowledge the pressure, then ask what timing or sale terms would help. Respectful boundaries build more trust than forced sympathy.
Be clear about what you can and can’t promise. If you need to inspect the home before discussing a firm offer, say so. If the seller asks whether you can close by a certain date, explain which steps affect that date instead of agreeing on the spot. Plain answers reduce confusion and prevent mismatched expectations.
Match your pace to the seller’s. A landlord who wants a quick exit may prefer direct questions and a clear next step. An estate representative may need time to involve other decision-makers. Ask who should join the next conversation, then confirm a specific follow-up action before ending the call.
After the call, review your notes for the seller’s exact language, concerns, and agreed next step. For example, note that the seller wants to discuss timing with a sibling before scheduling a walkthrough. That record helps you pick up the conversation naturally instead of asking the seller to repeat the same details.
Use a consistent call process to keep each seller conversation clear and focused. Strengthen your real estate seller-calling process with practical steps for planning and handling calls.
Lead Genie Outsourcing: Cold calling for real estate wholesalers
Lead Genie Outsourcing handles cold calling for real estate wholesalers and investors who need consistent seller conversations. Dedicated callers work 40 hours a week, and each caller gets 10,000 skip-traced, scrubbed records. Seller leads are qualified on reason to sell, timeline, condition, and asking price, with a call recording for review.
The guarantee is 30 qualified seller appointments a month, or dialing continues free until the target is met. The LGO CRM is free for 30 days, giving you a place to manage seller follow-up. If you want a steady calling process while you focus on evaluating deals, see how the calling process works.
Book a free 30-minute call to discuss your seller outreach.
Turn the Next Seller Call Into a Clear Next Step
Use your next seller conversation to test one improvement. Choose a question you tend to rush, then give the seller room to answer before moving on. Questions to ask motivated sellers work best as a conversation map, not a rigid script. Tailor follow-ups to the seller’s answers, and end each call with a clear next action both sides understand.
After the call, review where the conversation opened up and where it stalled. Did your wording invite a useful answer? Did you move too quickly to price? Make one practical adjustment before your next call. Over time, consistent notes and deliberate follow-up can help you identify which conversations merit another touch and which should move forward.
If you want support with seller outreach, take the next step and book a free 30-minute call with Lead Genie Outsourcing. Put the next conversation in motion.
Frequently Asked Questions
What questions should you ask a motivated seller when buying a house?
Ask who owns the property, who lives there now, and what the seller expects to remain after closing. These questions to ask motivated sellers uncover practical details beyond price. For example, confirm whether appliances, tenant belongings, or stored items are included. Ask how you can access the home for a walkthrough and whether another owner or decision-maker should join the next discussion.
How do you find out why a homeowner is selling?
Ask, “What would you like to change by selling this property?” This invites the homeowner to explain their goal, not just name a problem. If they say they want less responsibility, ask what responsibility they mean. If they mention a move, ask what needs to fall into place first. Keep personal questions tied to the sale and let the seller decide how much to share.
What questions reveal a seller’s timeline and urgency?
Ask what event the seller is working toward, when they hope to move, and whether anything could delay the sale. A planned job transfer, for example, may mean a different deadline than waiting for another home to become available. Clarify whether the seller needs a signed agreement, a move-out date, or a completed closing by that point. These milestones show what “soon” means in practice.
How should you ask about a property’s condition, repairs, and known defects?
Ask the seller to describe the home’s main systems and any known problems. “Has anything stopped working or needed repair since you’ve owned it?” can prompt details about the heating system, roof, plumbing, or past water issues. Ask whether a contractor has assessed the problem and whether the seller has notes or invoices. Keep reported issues separate from what you observe during your walkthrough.
What questions should you ask about the mortgage, liens, taxes, and other debts?
Ask what balances or unpaid amounts the seller knows about, then clarify which property they relate to. Request available statements or bills for the mortgage, property taxes, liens, and other property-related debts. Ask whether the amounts are current or still being updated. Use the records to identify questions to resolve before setting terms, and don’t treat the seller’s estimate as a final payoff amount.
How do you ask a seller about their asking price and flexibility?
Start by asking how the seller chose the asking price. Then ask what matters most to them: price, closing date, or another term. If they say the number is firm, ask what other terms they might consider. For example, the seller may value a closing date that fits their move. Base your offer on the property’s condition and deal numbers, not pressure or guesswork.
How can you build rapport with a motivated seller without using high-pressure tactics?
Ask permission to continue, listen without interrupting, and reflect one specific detail the seller shared. For example, say, “You mentioned coordinating repairs from another state. Is that the main issue?” Answer directly if the seller asks about your process. Don’t invent a deadline or push for an immediate decision. End by agreeing on a clear next step, such as a follow-up call or property walkthrough.
What questions should you ask a motivated seller before making a cash offer?
Before making a cash offer, confirm ownership, property access, occupancy, known condition issues, the seller’s target timing, and the price they’d consider. Ask whether anyone else must approve the sale and whether included items need to be addressed. Then compare the seller’s answers with your walkthrough notes and deal analysis. If key details conflict, clarify them before putting an offer in writing.
Ready to strengthen your seller outreach? Book a free 30-minute call.